Mumbai IT professional gets tax relief after employer fails to pay TDS
Headline by Prism · from 1 report
The Income Tax Appellate Tribunal in Mumbai ruled that an employee cannot be held liable for unpaid taxes when their employer has deducted the amount but failed to deposit it with the government.
 The Times of India
The brief
Written by software from the 1 report below.
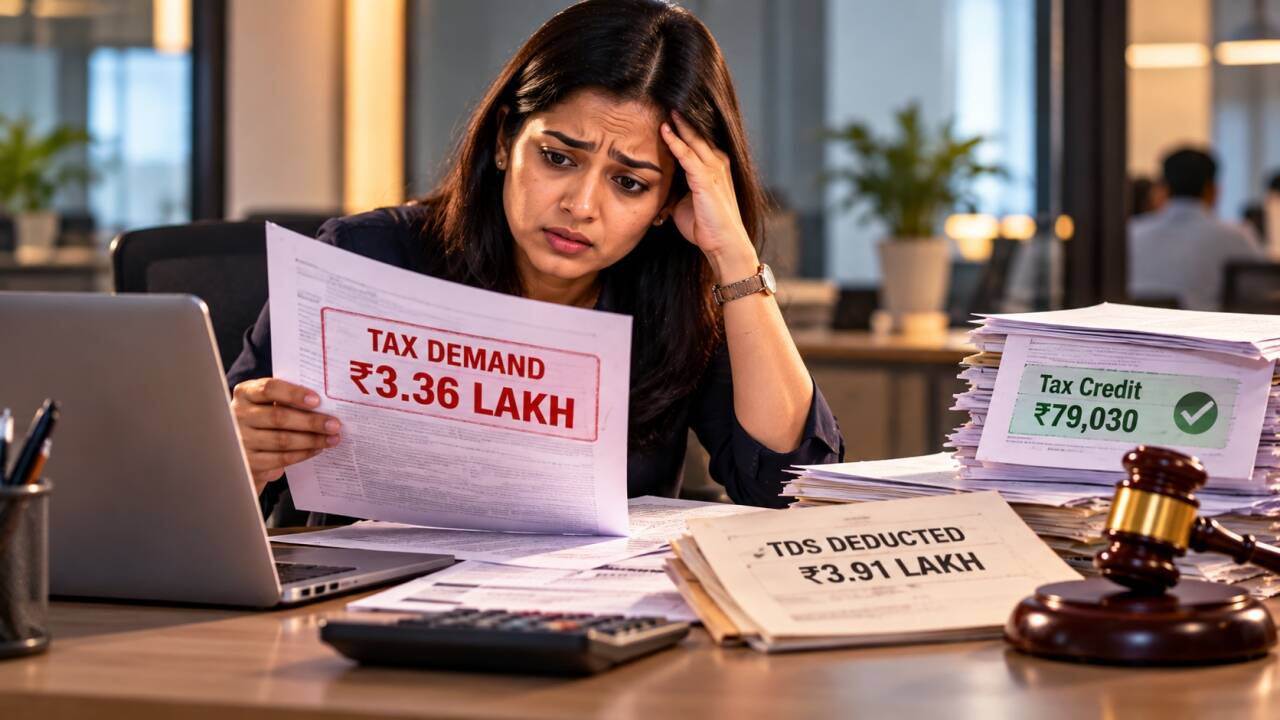
- An IT professional received a tax demand notice after her employer deducted TDS from her salary but did not remit it to the tax authorities.
- The Income Tax Appellate Tribunal ruled in the taxpayer's favor, stating that employees are not liable for an employer's failure to deposit withheld taxes.
- The decision allows the taxpayer to claim the full TDS credit upon verification of salary records and banking evidence.
- This ruling establishes that automated tax processing systems cannot deny legitimate claims if the taxpayer can prove the deduction occurred.
What to watch next
- Ongoing verification by the Assessing Officer to grant full TDS credit
- Potential impact of the ITAT ruling on future automated tax demand disputes
The points restate the reports; where one says why it matters, that is Prism's reading, not a reported fact.
Who said what
2 quotes · 1 outlet
Only words found exactly in the article are shown, attributed and linked to the line they came from.
Raghav Bajaj
Partner, Khaitan & Co
1 quote · 1 outlet
“By directing verification and grant of credit, the Tribunal recognises the evidentiary value of Form 16, salary records and banking trails. For taxpayers and practitioners, the implications are both reassuring and instructive,”
In the article
…remit it. Section 205 of the Income-tax Act, 1961 (corresponding to section 401 of Income-tax Act, 2025) draws a bright line: once tax is deducted, the obligation to remit it falls on the deductor, not the deductee. “ By directing verification and grant of credit, the Tribunal recognises the evidentiary value of Form 16, salary records and banking trails. For taxpayers and practitioners, the implications are both reassuring and instructive, ” he tells TOI. On the dispute resolution front, this decision makes clear that automated CPC processing under Section 143(1) - which matches TDS claims against Form 26AS - cannot be the final word where genuine…
Kuldip Kumar
Partner at Mainstay Tax Advisors LLP
1 quote · 1 outlet
“The legal position is now strongly supported by a consistent line of judicial decisions that, where tax has actually been deducted at source but has not been deposited by the deductor, the assessee should not be denied the corresponding TDS credit or be made liable to pay the same tax again, provided the assessee is able to establish that the tax was in fact deducted,”
In the article
…a useful reiteration of an important principle relating to TDS credit. There have been several other judgments of different Benches of the ITAT and various High Courts that have favoured the assessee in this regard. “ The legal position is now strongly supported by a consistent line of judicial decisions that, where tax has actually been deducted at source but has not been deposited by the deductor, the assessee should not be denied the corresponding TDS credit or be made liable to pay the same tax again, provided the assessee is able to establish that the tax was in fact deducted, ” Kumar tells TOI. Importantly, Kumar notes that this principle is not confined to tax deducted from salary. It can also apply to TDS deducted from other domestic payments, including contractor or professional fees,…
Coverage
1 outlet
All filed from India
NamedIndia · Centralised Processing Centre · Mumbai · Income Tax Appellate Tribunal · Khaitan & Co · Kuldip Kumar · Mainstay Tax Advisors LLP · Raghav Bajaj
The 1 report is listed beside the record.
Corrections and versions
A correction says what was wrong and why. Every earlier headline and brief of this record is kept.
Something wrong?
Say what, and it arrives with this record's address filled in. A correction is welcome.
Ask this story
Answers cite the 1 report above, or say they can't.